Categories
Home Buying Tips, VA Loan Guide, VA Loan Tips, Fort Stewart Area Homes, Fort Stewart PCS, Fort Stewart Real Estate, Military Relocation, Military Relocation Specialist, Coastal Georgia Real Estate, Coastal Georgia HomesPublished September 11, 2026
BAH vs. Mortgage for Fort Stewart Military Buyers
Written by Kevin Thomas
Most conversations about BAH and mortgages focus on whether this month's allowance covers this month's payment. That's the wrong time horizon. The more useful question is what happens to that comparison over a full tour — and there are two lesser-known BAH rules that tilt the answer more toward buying than most Fort Stewart families realize.
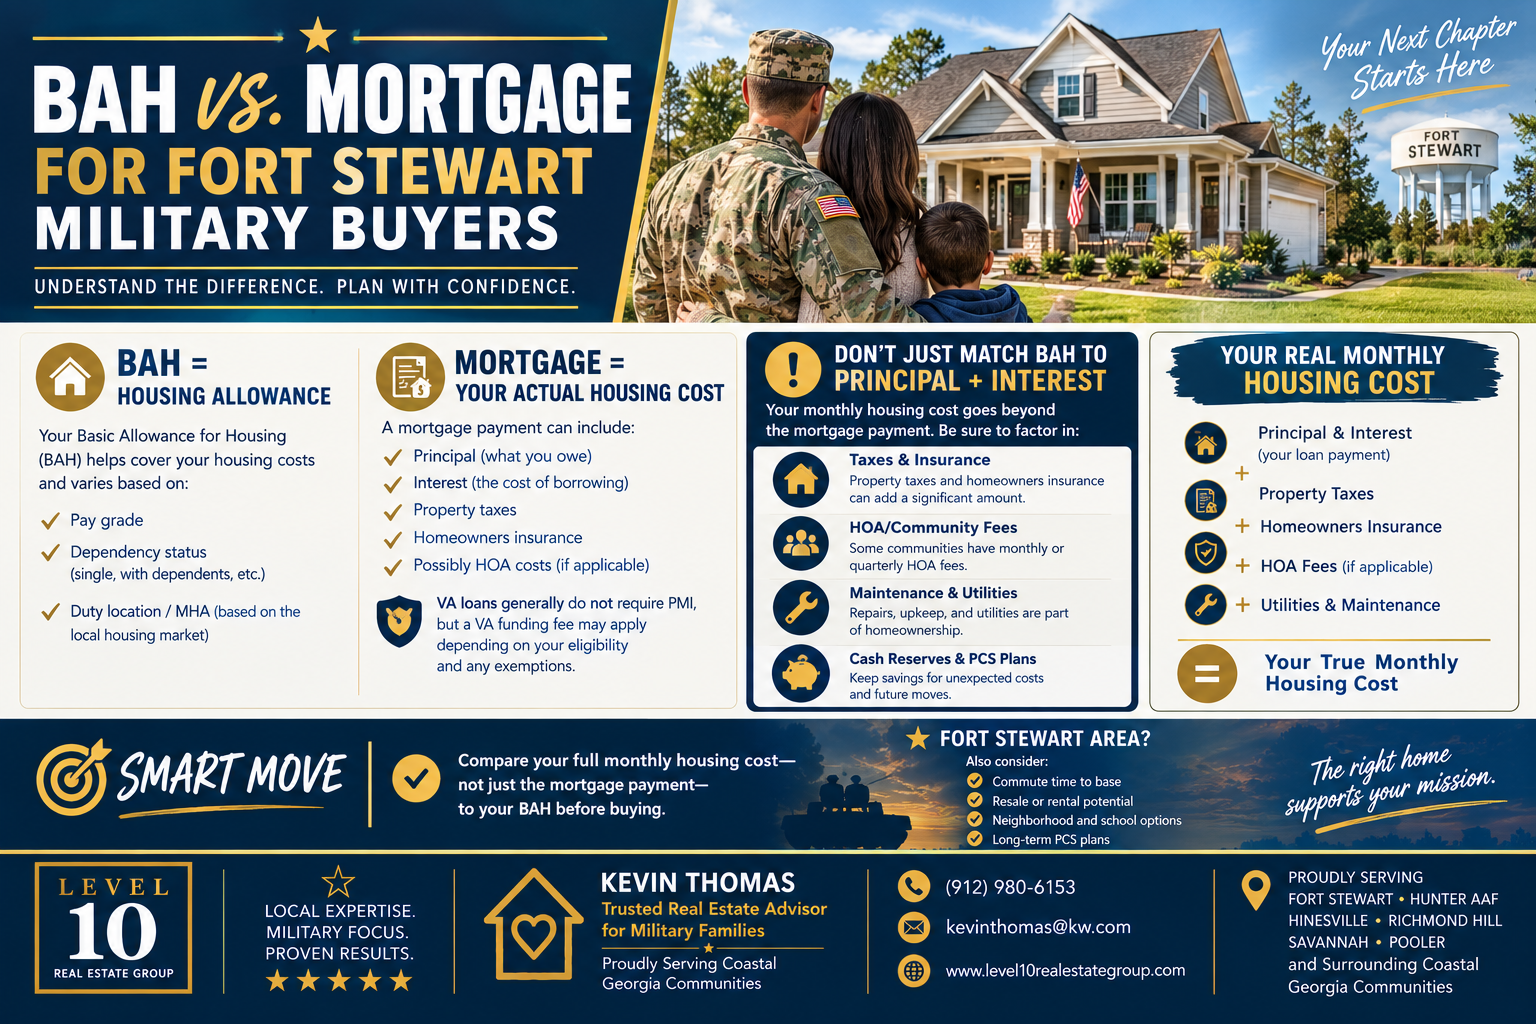
👉 BAH comes with individual rate protection — once you're locked in, it cannot drop below what you received the prior year, even if area housing costs fall — while a fixed-rate VA mortgage payment is locked in the same way. Renters get no equivalent protection against a landlord raising rent.
Here's how these two locked-in numbers actually compare over time, plus what dual-military households need to know.
The Rule Most Buyers Have Never Heard Of: Individual Rate Protection
Under Department of Defense policy, your BAH cannot decrease year over year as long as your eligibility status doesn't change — you're entitled to whichever is higher: the newly published rate each January, or what you were already receiving. If the local housing market cools and BAH rates for Fort Stewart's area drop the following year, your personal rate stays exactly where it was.
This protection ends only if you PCS, change pay grade, or have a dependency status change that triggers a recalculation. Short of one of those events, your BAH is a locked floor for as long as you're at that duty station — which matters enormously when you're comparing it against a mortgage payment that's also locked, assuming you financed at a fixed rate.
Two Locked Numbers vs. One That Moves Freely
A fixed-rate VA mortgage payment doesn't change for the life of the loan. Combine that with BAH's rate protection, and a Fort Stewart homeowner is comparing two numbers that are both effectively frozen for the duration of the assignment — the actual gap between them either holds steady or improves in the homeowner's favor if BAH rates rise in a future year.
Rent has no equivalent protection. A landlord can raise rent at lease renewal based on nothing more than market conditions, and a renter absorbs that increase directly out of pocket if BAH doesn't rise to match it in the same cycle. Over a two- or three-year tour, this asymmetry compounds — the mortgage-holder's locked payment increasingly looks like the more predictable position, even before accounting for equity building.
What This Means for Timing a Purchase
If BAH rates for Fort Stewart's housing area rise before you buy, that's a rate you get to lock in for as long as you stay — buying earlier in a tour, once you know you're settled, captures more of that protected window than buying in your final year. This isn't a reason to rush a purchase decision, but it is a reason to run the numbers again if you've been renting for a while and assumed the comparison hadn't changed since you arrived.
Dual-Military Households: A Housing Budget Most Calculators Miss
If both spouses in your household are service members, each of you draws your own individual BAH — there's no combined or split benefit, and marriage doesn't reduce either person's entitlement. If you have no dependents, you each receive the without-dependents rate for your own pay grade and duty station. If you have a dependent child, the couple designates one member to receive the with-dependents rate, typically the higher-ranking spouse, while the other continues at their individual rate.
The practical result: many dual-military Fort Stewart households are working with two BAH streams, not one, meaningfully expanding what's realistically affordable compared to a generic single-income BAH calculation. If you're a dual-military couple and you've only run the numbers off one BAH entry, you're likely underestimating your actual buying power.
Where This Still Requires the Basic Math
None of this changes the underlying reality that a lender's principal-and-interest quote isn't your full housing cost — property taxes, insurance, HOA dues, and a maintenance reserve still belong in any honest comparison against BAH, dual-income or not. The strategic point here is about the direction these two numbers move over time, not a replacement for running your specific fully loaded payment before you make an offer.
Why Work With Kevin Thomas
Understanding how BAH's own protections stack up against a fixed mortgage payment — and what that means for timing and dual-military households — is the kind of strategic detail that changes how confidently you approach a purchase decision. Kevin Thomas is a trusted buyer's agent and marketing strategist serving Coastal Georgia, with deep experience helping Fort Stewart families, including dual-military households, understand their real buying power.
Working with Kevin means:
✔️ A buying power estimate that accounts for both BAH streams in a dual-military household ✔️ Straight talk about how rate protection and fixed financing compare over a full tour ✔️ Honest guidance on timing a purchase around your specific BAH and rank situation ✔️ A fully loaded monthly cost estimate, not just a principal-and-interest quote ✔️ Support translating your household's real numbers into a confident search
Your Next Step
Call or text Kevin Thomas: (912) 980-6153 Know exactly how your BAH situation — single-income or dual-military — stacks up against a real mortgage payment before you start touring homes.
Kevin Thomas with Level 10 Real Estate Group helps Fort Stewart families turn BAH into a confident, strategic homebuying decision.
Karyn Thomas
Lead Listing Agent/ Co-Team Owner | Level 10 Real Estate Group | Keller Williams Coastal Area Partners
or another way