Categories
VA Loan Guide, VA Loan Tips, Military Relocation, Fort Stewart Real Estate, Fort Stewart PCS, Fort Stewart Area Homes, Buyer Guides, Home Buying TipsPublished August 30, 2026
Can You Buy Your Next Home Before Selling Your Current Home in Coastal Georgia?
Written by Kevin Thomas
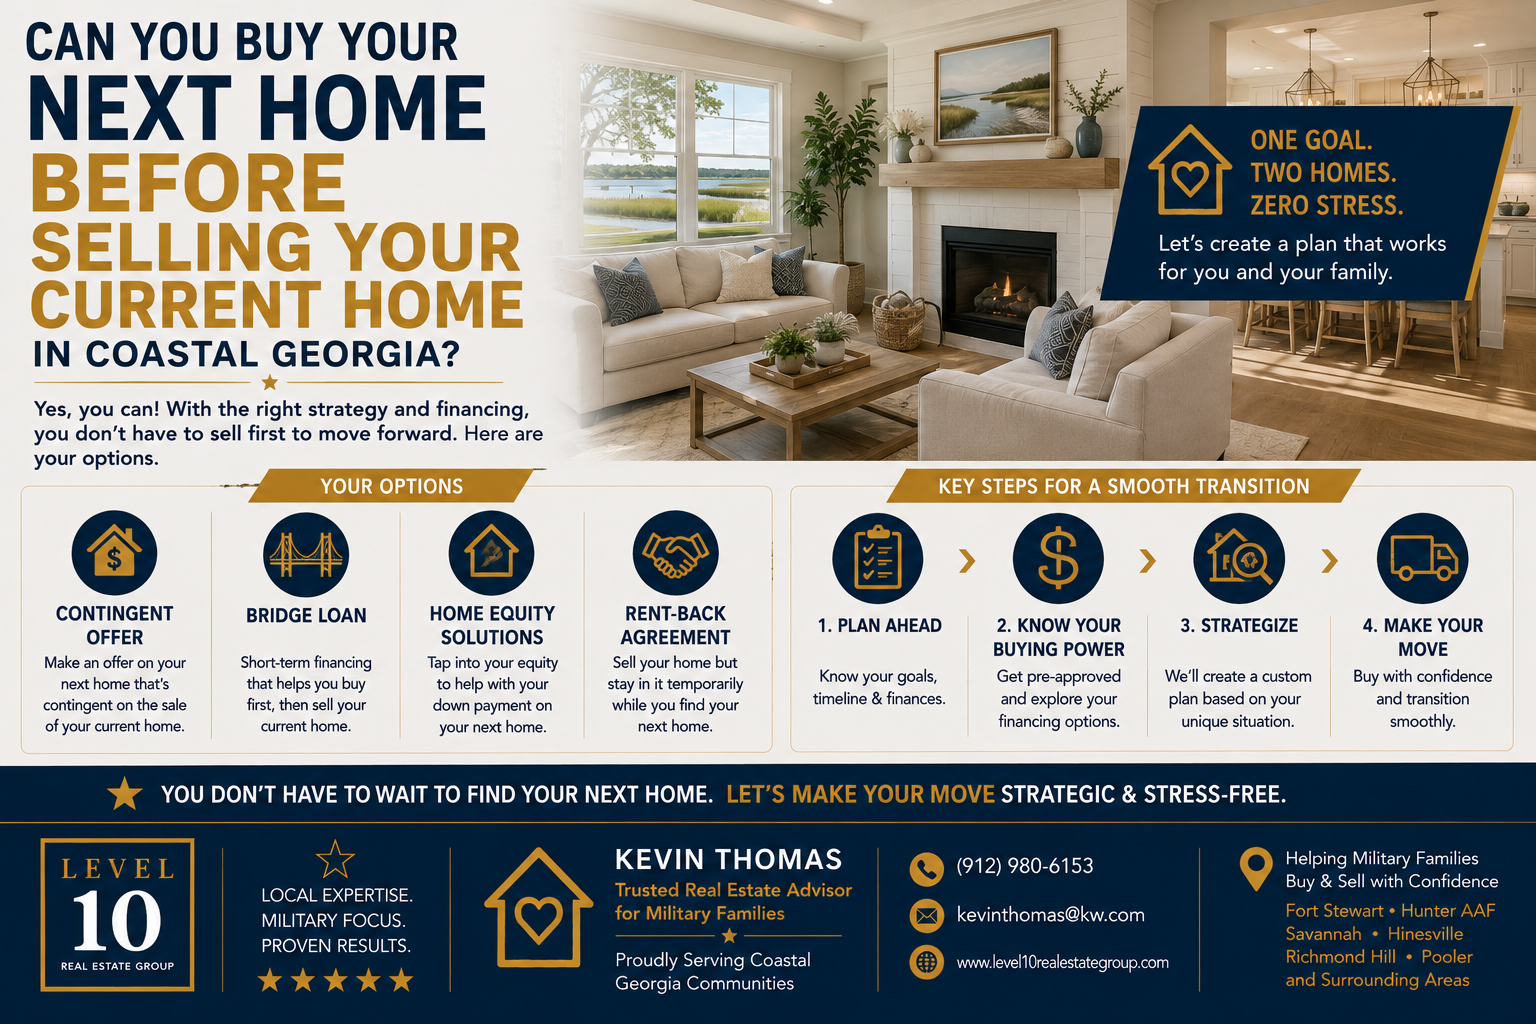
For a lot of civilian buyers, this is a lifestyle preference. For a lot of Fort Stewart families, it's a necessity — PCS report dates don't wait for a home sale to close, and the math on selling timelines we've covered before makes buying first the only realistic option in many cases. The good news: VA Loans have a specific mechanism built for exactly this situation.
👉 Yes — VA allows you to hold two active VA loans at once through second-tier entitlement, but whether you actually qualify for the new mortgage while still carrying the old one depends heavily on how well-documented your departing residence's rental income is.
Here's how the entitlement math and the qualifying math actually work.
Why This Question Matters So Much for Fort Stewart Families
We've covered before that the average time from PCS orders to report date runs around 60 days, while the average home sale timeline runs closer to 68 days. For a lot of military families, the numbers simply don't allow selling first and buying second — which makes understanding how to qualify for a new home while still owning the old one a genuinely practical necessity, not a hypothetical scenario.
Second-Tier Entitlement: How VA Lets You Hold Two Loans at Once
VA entitlement comes in two parts: basic entitlement, set at $36,000, and bonus entitlement (also called second-tier entitlement), which extends your zero-down borrowing power further. The VA allows you to hold two active VA loans simultaneously — using whatever entitlement remains uncommitted after your first loan to secure the second.
Here's how the math works. Your zero-down borrowing ceiling on a new loan equals roughly four times your remaining entitlement, capped by the loan limit for the county you're purchasing in. Using a representative standard county loan limit of $832,750, your maximum entitlement in that county would be $208,187. If you've already committed $75,000 of entitlement to your current home, you'd have $126,625 remaining — and that remaining figure is what determines how much you can borrow with $0 down on your next home.
This is genuinely useful information to get in front of a lender early — knowing your remaining entitlement before you start house hunting tells you exactly what price range you can pursue with no down payment on the new purchase.
The DTI Challenge: Qualifying With Two Mortgage Payments
Entitlement solves the down payment question. Debt-to-income qualification is the separate hurdle, and it comes down almost entirely to how your departing residence's rental income is documented.
If you have two years of documented rental history on your tax returns (Schedule E), lenders can use 75% of that rental income to offset your departing residence's mortgage payment in your DTI calculation — meaningfully improving your ability to qualify for the new loan while still carrying the old one.
If you don't have two years of history yet, most lenders won't offset the existing payment at all — both mortgage payments count fully against your DTI, which can make qualifying for the new loan considerably harder, depending on your income and other obligations.
A signed 12-month lease is the strongest available documentation if you don't yet have two years of rental history. Without one, a lender can order a Form 1007 Comparable Rent Schedule from an appraiser, which estimates market rent for the property even without an actual signed lease in hand.
VA also evaluates residual income — a measure of what's left over after all your obligations to cover basic living expenses — on every loan. Strong residual income can help offset a DTI ratio that looks tighter on paper once you're carrying two mortgage payments.
What If You Don't Have Two Years of Rental History Yet?
This is the scenario that catches the most Fort Stewart families off guard: converting your current home to a rental right before applying for a new VA loan often means both payments hit your DTI in full, since the two-year documented history requirement simply hasn't been met yet. If this describes your situation, get a signed lease in place as early as possible and talk to your lender well before you're under contract on a new home, so you know exactly where your qualifying numbers stand.
Other Practical Paths: Bridge Financing and Rent-Back Agreements
VA Loans don't offer bridge financing directly, but a conventional bridge loan or a HELOC against your current home's equity can supply funds for a down payment or closing costs on the new purchase while your current home is still on the market — a path worth discussing with a lender if your entitlement and DTI math don't quite line up on their own.
A rent-back agreement, negotiated with the buyer of your current home, can also bridge a timing gap if your new home closes before your PCS report date fully lines up with your old home's sale.
How to Actually Plan This Before You're Under Pressure
Get your remaining entitlement calculated by a lender before you start house hunting — this tells you your real zero-down ceiling on the new purchase.
Start the lease process on your current home as early as realistically possible if you're planning to rent it out, since a signed lease is your strongest documentation if you don't yet have two years of rental history.
Have an honest DTI conversation with your lender before you're emotionally invested in a specific new home — knowing whether both payments will count in full changes what you can realistically afford to pursue.
Why Work With Kevin Thomas
Buying before selling is genuinely possible for military families, but it requires understanding both your entitlement math and your qualifying math well before you're under contract pressure. Kevin Thomas is a trusted buyer's agent and marketing strategist serving Coastal Georgia, with deep experience helping Fort Stewart families navigate second-tier entitlement, rental income documentation, and the timing gap between buying and selling.
Working with Kevin means:
✔️ Early entitlement calculation so you know your real zero-down ceiling ✔️ Guidance on documenting rental income the right way before you apply for a new loan ✔️ Honest conversations about DTI before you're attached to a specific home ✔️ Awareness of bridge financing and rent-back options when the timing is tight ✔️ Support planning your next purchase around your real numbers, not assumptions
Your Next Step
Call or text Kevin Thomas: (912) 980-6153 If you need to buy your next Coastal Georgia home before your current one sells, get your real entitlement and qualifying numbers early.
Kevin Thomas with Level 10 Real Estate Group helps Fort Stewart families buy with confidence, even when selling hasn't happened yet.
Karyn Thomas
Lead Listing Agent/ Co-Team Owner | Level 10 Real Estate Group | Keller Williams Coastal Area Partners
or another way