Categories
VA Loan Guide, Military Relocation, Buyer Guides, Fort Stewart Area Homes, Fort Stewart PCS, Fort Stewart Real Estate, Home Buying TipsPublished October 8, 2026
Can You Use Your VA Loan More Than Once?
Written by Kevin Thomas
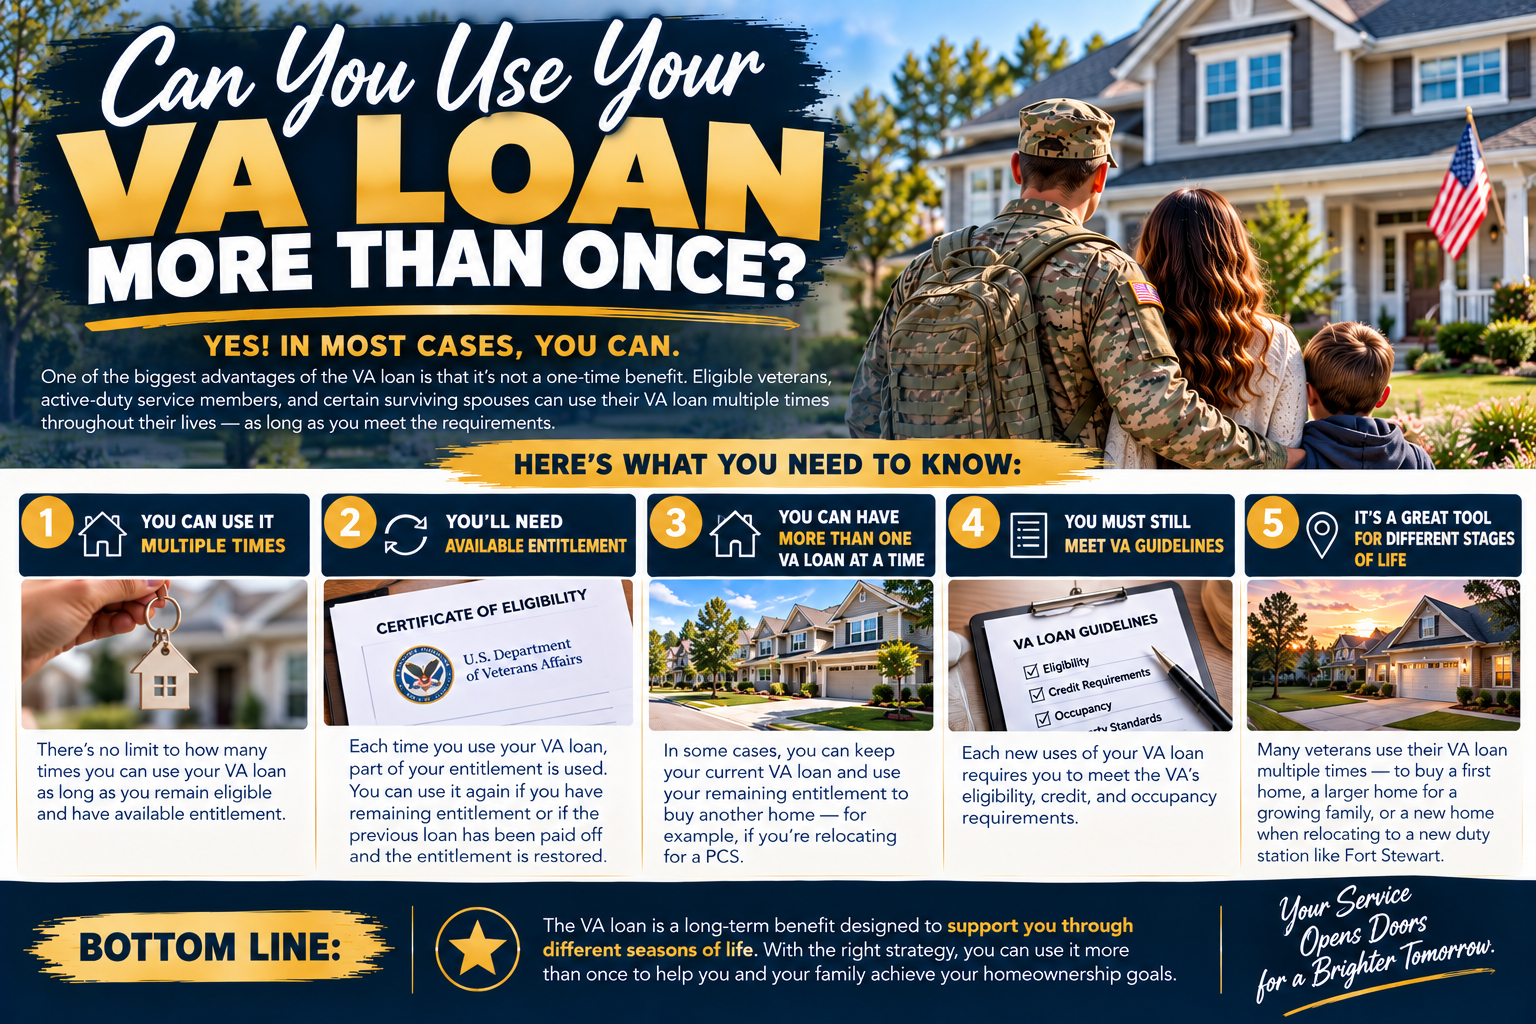
Short answer: yes — and not just twice. There's no lifetime limit on how many times you can use your VA Loan benefit, which is exactly why so many career military families buy, sell, and buy again at every duty station. Here's the direct answer, plus one distinction about refinancing that catches even experienced VA borrowers off guard.
👉 There is no cap on how many times you can use your VA Loan entitlement across a career — but refinancing an existing VA loan through an IRRRL doesn't use a new entitlement at all, and carries a flat 0.5% funding fee regardless of how many times you've used your benefit before.
Here's how it actually works.
Yes, You Can Use It Again — And Again
Selling a home and paying off the VA loan attached to it automatically restores your full entitlement, with no separate application required. This is the pattern a lot of career service members follow without even thinking of it as "reusing" a benefit: buy near one duty station, sell when orders move you, and the VA loan option is simply there again at the next one. There's no limit on how many times this cycle can repeat over a 10, 20, or 30-year career.
The one thing that does change after your first use is your funding fee tier — subsequent purchases at less than 5% down carry a higher funding fee (currently 3.3%) than a first-time use (2.15%), though that gap disappears entirely once you put 5% or more down.
The Distinction Most Buyers Don't Know: Refinancing Isn't "Using It Again"
If you're refinancing your current VA loan rather than buying a new home, that's a fundamentally different transaction — and it works differently than a new purchase. A VA Interest Rate Reduction Refinance Loan (IRRRL) reuses the exact entitlement already attached to your existing loan, rather than requiring a new or restored entitlement. It also carries a flat 0.5% funding fee, regardless of how many times you've used a VA loan before — a meaningfully lower cost than even a first-time purchase funding fee, because you're not taking out a new purchase loan, just adjusting the terms of one you already have.
This means refinancing doesn't "count" against your entitlement usage history the way buying a new home does — worth knowing if you're confusing the two when you hear someone mention funding fee tiers.
What This Looks Like Across a Full Career
A service member might buy their first home with $0 down and a 2.15% funding fee, sell it a few years later at the next PCS with entitlement restoring automatically, buy again with a 3.3% funding fee at 0% down (or 1.50% at 5% down), refinance that same loan years later via IRRRL at a flat 0.5% fee without touching their entitlement at all, and still have the option to buy again at a future duty station using the exact same benefit. Each purchase is independently evaluated — your credit, income, and funding fee status reset with the facts of that specific transaction, while a refinance simply adjusts what you already have.
What to Actually Confirm Before Your Next Transaction
If you're buying again, confirm your entitlement has been restored by checking your Certificate of Eligibility with your lender, particularly if your last sale closed recently.
If you're refinancing, confirm you're being quoted the IRRRL's flat 0.5% funding fee — not a purchase-level fee that doesn't apply to your transaction type.
Run the down payment math on a repeat purchase if you're deciding between $0 down and 5% down, since that single decision determines whether the subsequent-use funding fee penalty applies to you at all.
Why Work With Kevin Thomas
Knowing exactly where you stand — entitlement restored, funding fee tier, or a refinance that doesn't touch either — is what lets you use your VA benefit with real confidence, transaction after transaction. Kevin Thomas is a trusted buyer's agent and marketing strategist serving Coastal Georgia, and a U.S. Army veteran with firsthand experience helping military families use their VA Loan benefit again and again across a full career.
Working with Kevin means:
✔️ Clear guidance on your entitlement status before you assume it's fully restored ✔️ Straight talk about the difference between a new purchase and a refinance ✔️ Funding fee math run accurately for your specific transaction type ✔️ Lender referrals experienced with repeat VA buyers and IRRRL refinances ✔️ Support using your VA benefit confidently, however many times you need it
Your Next Step
Call or text Kevin Thomas: (912) 980-6153 Whether it's your second VA Loan or your fifth, know exactly where you stand before you move forward.
Kevin Thomas with Level 10 Real Estate Group helps military families use their VA Loan benefit with confidence, every time.
Karyn Thomas
Lead Listing Agent/ Co-Team Owner | Level 10 Real Estate Group | Keller Williams Coastal Area Partners
or another way