Categories
VA Loan Tips, VA Loan Guide, Military Relocation, Military Relocation Specialist, Fort Stewart Real Estate, Fort Stewart PCS, Fort Stewart Area Homes, Buyer Guides, Coastal Georgia Homes, Coastal Georgia Real EstatePublished September 7, 2026
Using Your VA Loan Twice in Coastal Georgia
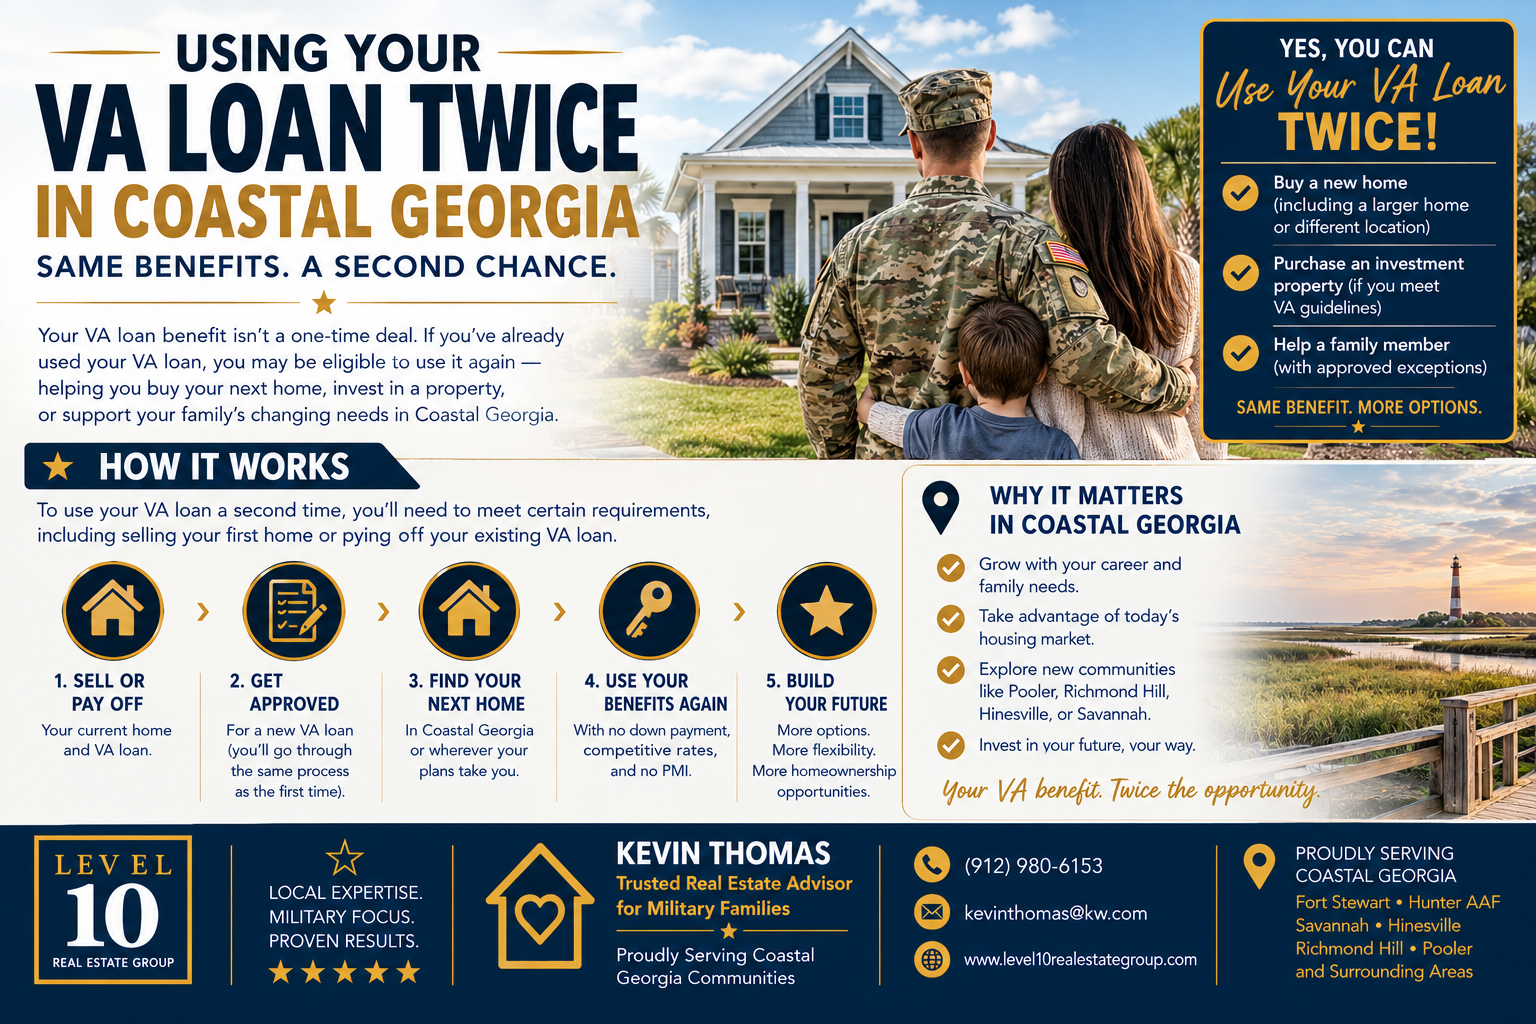
A full military career often means multiple PCS moves, and for a lot of Fort Stewart families, that means buying a home with a VA Loan more than once. The benefit itself doesn't run out — but the cost of using it a second time isn't identical to the first, and knowing the difference before you go under contract again matters.
👉 If you sold your last home and paid off that VA loan in full, your entitlement is automatically restored with no application needed — but if you're putting less than 5% down on your next purchase, your funding fee jumps from 2.15% to 3.3%, simply because the VA now classifies you as a subsequent user.
Here's what actually changes the second time around, and what doesn't.
The Good News First: Your Entitlement Comes Back
If you sold your previous home and paid off the VA loan attached to it, your full entitlement is restored automatically — no separate application, no waiting period tied to the sale itself. This is exactly the pattern most career military families follow: buy near one duty station, sell when orders move you, buy again near the next one, using the same VA benefit each time.
If you paid off the loan but kept the property — turning it into a rental, for example, rather than selling it — restoration works differently. The VA allows a one-time restoration of entitlement in this scenario, usable exactly once in your lifetime, by filing VA Form 26-1880 along with proof the loan was paid in full. After that one-time use, any future entitlement restoration requires disposing of every property you've ever financed with a VA loan first.
What Actually Changes: The Funding Fee
This is the detail that surprises a lot of repeat VA buyers. The VA funding fee schedule treats you differently once you've used your benefit before — even if you sold that home years ago and have zero remaining obligation on it.
At less than 5% down, first-time users currently pay a 2.15% funding fee, while subsequent users pay 3.3% — a meaningful difference on a Coastal Georgia home price. At 5% or more down, the gap disappears entirely — both first-time and subsequent users pay 1.50%, and at 10% or more down, both pay 1.25%.
The practical takeaway: if you're financing with $0 down on your second (or third, or fourth) VA loan, expect a noticeably higher funding fee than you paid the first time — but if you're able to put even 5% down, that penalty for being a repeat user disappears completely.
What Does NOT Change the Second Time
Your zero-down borrowing power itself doesn't disappear — full entitlement restoration means you can finance with $0 down again, exactly as you did the first time, subject to your county's loan limit. VA's occupancy and property condition standards apply identically regardless of how many times you've used the benefit before. Disability-rated veterans remain exempt from the funding fee entirely, on a first loan or a fifth.
The Career-Long Pattern Fort Stewart Families Actually Follow
For many service members, this isn't a one-time question — it's a recurring one across an entire career. Buy near your first duty station, sell when PCS orders come, restore entitlement automatically at closing, buy again at the next post. Each cycle is genuinely independent: your credit, your income, and your funding fee status all get reevaluated fresh each time, with only the funding fee tier actually carrying forward as a consequence of prior use.
If you're weighing whether to sell your current home outright versus converting it to a rental before your next PCS, this funding fee difference is worth factoring in alongside the second-tier entitlement and DTI considerations that come with holding two properties at once — selling cleanly resets your funding fee eligibility question just as cleanly as it restores your entitlement.
What to Actually Do Before Your Next VA Purchase
Confirm your entitlement has actually been restored before assuming it has — ask your lender to verify your Certificate of Eligibility reflects full entitlement, particularly if your last VA-financed home sale closed recently.
Run the funding fee math at $0 down versus 5% down before deciding on your down payment strategy — the gap between 3.3% and 1.50% is large enough to actively shape that decision for a repeat user.
If you paid off a VA loan without selling the property, confirm whether you've already used your one-time restoration exception before assuming it's still available — this benefit doesn't reset itself.
Why Work With Kevin Thomas
Buying with a VA Loan for a second or third time comes with a few details that catch even experienced military buyers off guard — knowing them ahead of time protects your budget. Kevin Thomas is a trusted buyer's agent and marketing strategist serving Coastal Georgia, with deep experience helping Fort Stewart families navigate repeat VA purchases across multiple PCS cycles.
Working with Kevin means:
✔️ Clear guidance on your entitlement status before you assume it's fully restored ✔️ Funding fee math run both ways, so your down payment decision is an informed one ✔️ Straight talk about the one-time restoration exception if you've kept a prior property ✔️ Lender referrals experienced with repeat VA buyers and multi-PCS careers ✔️ Support building a purchase strategy around your real numbers, not assumptions
Your Next Step
Call or text Kevin Thomas: (912) 980-6153 Using your VA Loan again? Know your real entitlement status and funding fee before you go under contract.
Kevin Thomas with Level 10 Real Estate Group helps Fort Stewart families use their VA Loan benefit wisely, every time they PCS.
Karyn Thomas
Lead Listing Agent/ Co-Team Owner | Level 10 Real Estate Group | Keller Williams Coastal Area Partners
or another way