Categories
VA Loan Guide, VA Loan Tips, Home Buying Tips, Home Selling Tips, Coastal Georgia Homes, Coastal Georgia Real Estate, Military Relocation, Buyer GuidesPublished August 31, 2026
What Credit Score Do You Actually Need for a VA Loan in Coastal Georgia?
Written by Kevin Thomas
Ask five different lenders what credit score you need for a VA Loan and you'll likely get five different numbers. That's not inconsistent advice — it's an accurate reflection of how this actually works, and understanding why is the key to not ruling yourself out of homeownership based on a number that may not even apply to you.
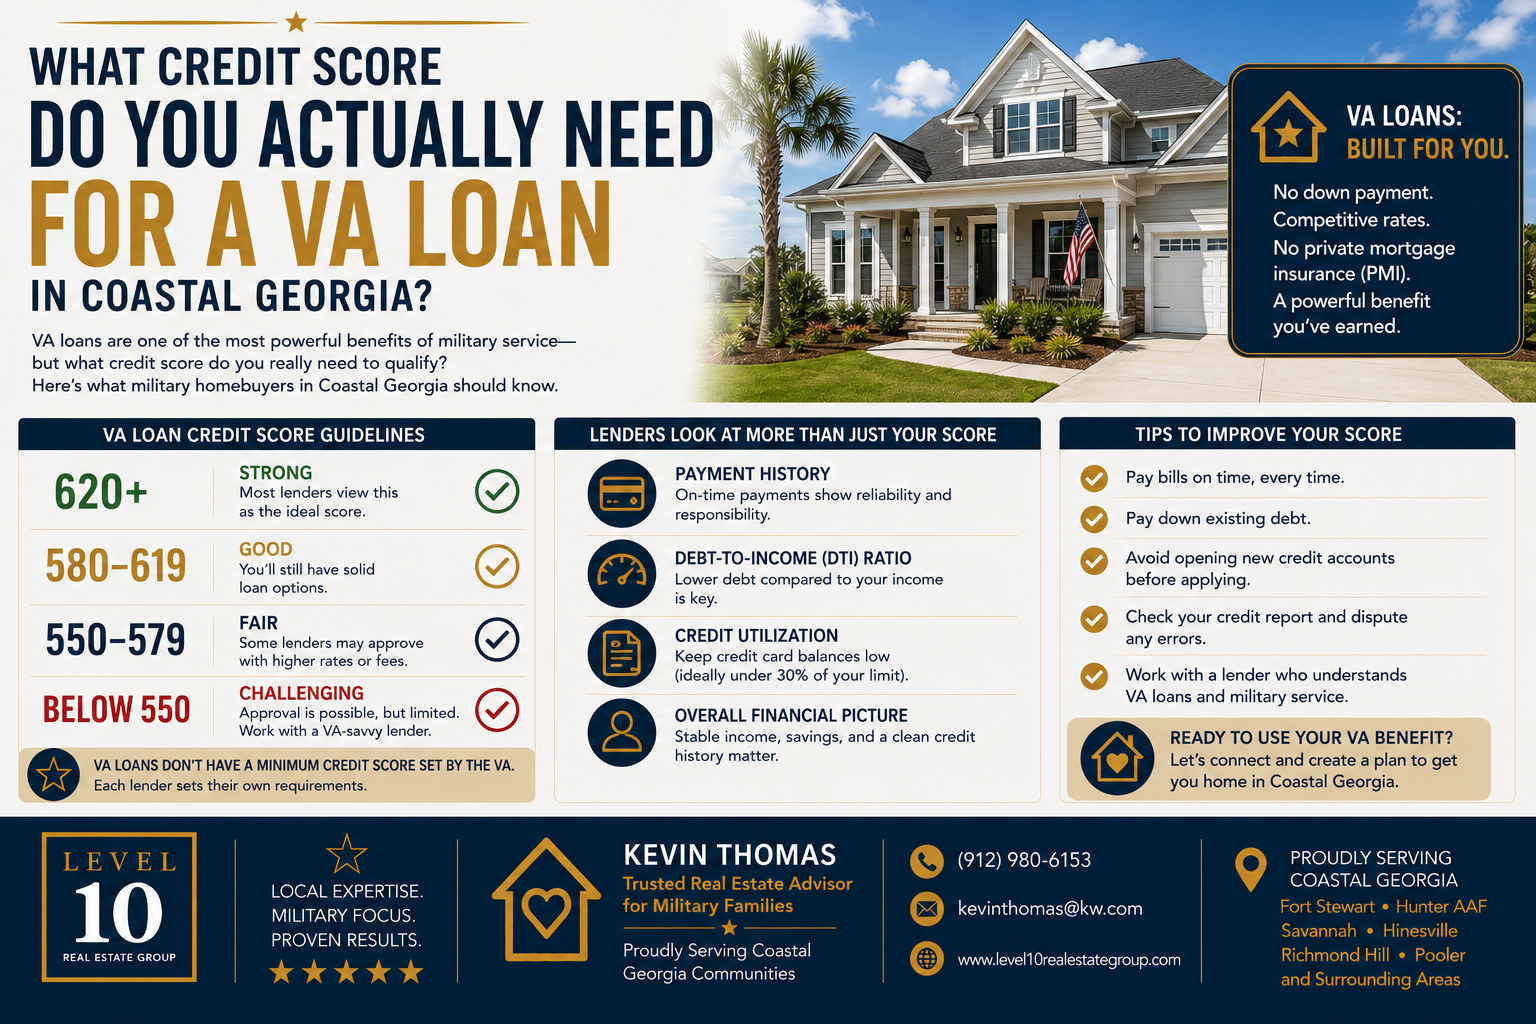
👉 The VA itself sets no minimum credit score at all — every number you've heard, whether it's 580, 600, or 620, is a requirement set by an individual lender, not a VA rule. That means the real answer depends entirely on which lender you're talking to.
Here's what actually determines whether you qualify.
The VA's Actual Position: No Minimum, Period
This is worth stating plainly because it's so often misunderstood: the VA does not require a minimum credit score for VA Loan eligibility. The VA guarantees a portion of the loan — protecting the lender against loss — but it leaves the actual credit qualification standards to the lenders who fund the loans and carry the day-to-day risk.
Every credit score minimum you've seen advertised is a lender overlay — a requirement that specific lender chose to impose on top of VA's actual guidelines, not a government-set floor that applies universally.
What Lenders Actually Require: The Real Range
Because overlays vary lender to lender, published minimums across major VA lenders currently range from around 550 to 640, with 620 being the most commonly published minimum among mainstream lenders. Many lenders set their threshold somewhere in the 580–620 range.
Some VA-specialty lenders will go considerably lower — down to around 500 — if the rest of the loan file is strong enough to support automated underwriting approval. This is exactly why it's worth shopping more than one lender rather than assuming a single "no" settles the question. A borrower turned down by one lender's 620 overlay may be approved outright by a VA-specialty lender with a more flexible threshold and a strong overall file.
Why Credit Score Isn't the Whole Story
Approval isn't based solely on a three-digit number. Documented income strength, verified reserves, and a clean recent payment history can meaningfully offset a marginal credit score on many VA loan files. Residual income — the cushion left over after all your obligations are covered — is evaluated on every VA loan and can help support approval even when the credit score alone looks borderline to a specific lender's overlay.
This is part of why VA Loans remain more accessible than many buyers assume, even for those who don't have pristine credit: the underwriting picture is genuinely holistic, not a single pass/fail gate.
Building Credit From Scratch: The Alternative Tradeline Path
This is a detail that surprises a lot of younger service members and first-time buyers who simply haven't had time to build a traditional credit history yet: VA Loans don't require a minimum number of tradelines or even a traditional credit score at all. Borrowers without enough conventional credit history can qualify through manual underwriting, using alternative tradelines in place of a FICO score.
Alternative tradelines include rent payments, utility bills, insurance premiums, and cell phone payments — each requiring 12 consecutive months of documented, on-time payment history. Rent is the most heavily weighted of these, and most lenders offering this path require 3–4 qualifying tradelines to support a manual underwrite approval.
One important catch: a single late payment within that 12-month window can disqualify that specific tradeline entirely — and a late rent payment is especially damaging to this path, given how heavily it's weighted. Not every lender offers manual underwriting with alternative tradelines, so confirming this capability upfront, before you get attached to a specific lender, matters if this describes your situation.
One Thing Credit Score Does NOT Affect: The VA Funding Fee
Worth clarifying directly: the VA funding fee is based entirely on your down payment amount and whether you've used your VA entitlement before — never on your credit score. A borrower with a 580 score and a borrower with an 800 score financing the same loan amount with the same down payment pay the identical funding fee. Credit score affects your approval odds and your interest rate — not this specific cost.
What to Actually Do Before You Apply
Shop more than one lender. Given how much overlays vary, a rejection or a discouraging quote from one lender doesn't tell you what every lender will say.
Check your credit report early, well before you're under contract on a home, so you have time to address anything inaccurate or resolve small issues before they factor into a lender's decision.
Avoid any late payments in the 12 months before applying, particularly on rent if you're pursuing the alternative tradeline path — this window is unforgiving of even a single late payment.
Ask directly about manual underwriting and alternative tradelines if you have a thin credit file — not every lender offers this path, and it's worth confirming before you assume you don't qualify.
Why Work With Kevin Thomas
Knowing which lenders actually fit your specific credit picture — rather than assuming one overlay speaks for the whole industry — can be the difference between feeling shut out of homeownership and finding the right fit quickly. Kevin Thomas is a trusted buyer's agent and marketing strategist serving Coastal Georgia, with deep experience connecting military families and first-time buyers with lenders whose overlays actually match their situation.
Working with Kevin means:
✔️ Lender connections that match your actual credit profile, not a generic referral ✔️ Guidance on manual underwriting and alternative tradelines if your credit file is thin ✔️ Straight talk about what a marginal score does and doesn't rule out ✔️ Clarity on what actually affects your funding fee versus what doesn't ✔️ Support finding the right path to qualification, even if your first lender said no
Your Next Step
Call or text Kevin Thomas: (912) 980-6153 Don't let one lender's overlay convince you that homeownership isn't possible — find out what your real options actually are.
Kevin Thomas with Level 10 Real Estate Group helps Coastal Georgia buyers find the lender that actually fits their credit picture, not just the first answer they hear.
Karyn Thomas
Lead Listing Agent/ Co-Team Owner | Level 10 Real Estate Group | Keller Williams Coastal Area Partners
or another way