Categories
Home Buying Tips, Coastal Georgia Homes, Coastal Georgia Real Estate, Insurance, VA Loan Tips, VA Loan Guide, Buyer GuidesPublished August 18, 2026
Why Homeowners Insurance Can Change What You Can Afford in Coastal Georgia
Written by Kevin Thomas
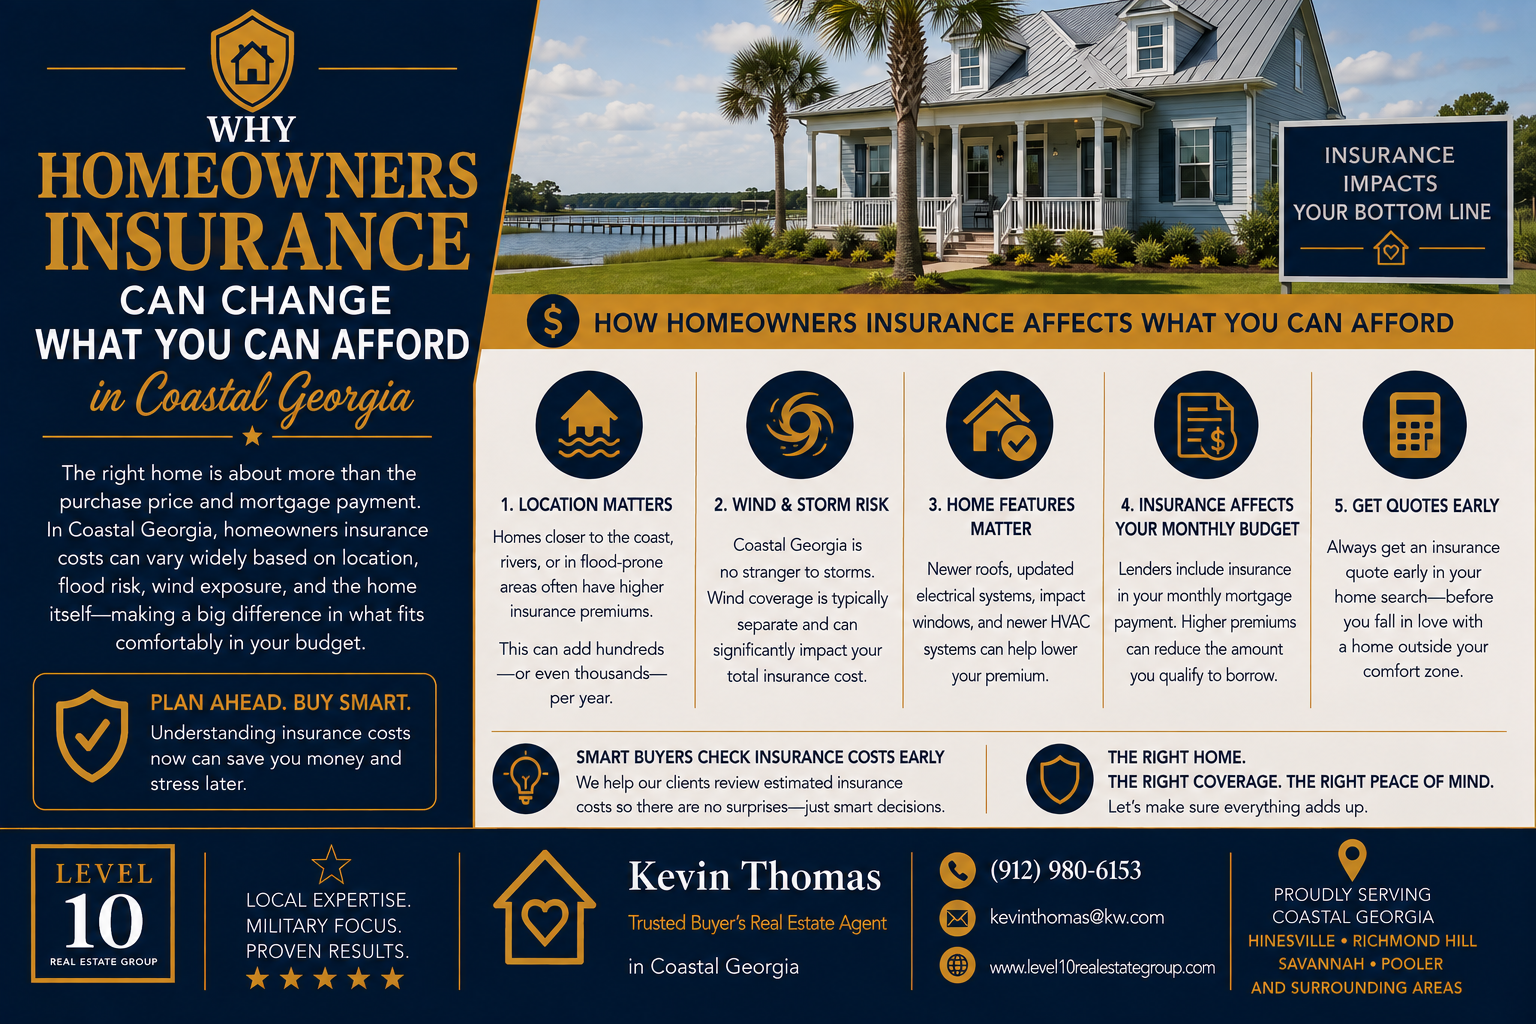
Most buyers think of homeowners insurance as a bill that shows up after closing. It's actually one of the inputs your lender uses to calculate how much home you qualify for in the first place — and in today's Coastal Georgia insurance market, that number is moving in a direction that's shrinking buying power for homes that look identical on paper.
👉 Homeowners insurance is part of your lender's debt-to-income calculation before you ever close — meaning a higher premium doesn't just cost you more monthly, it can directly reduce the loan amount you qualify for on the exact same house.
Here's how that mechanism actually works, what's happening in this market right now, and how to get some of that buying power back.
How Insurance Actually Shrinks Your Buying Power
Lenders qualify buyers using PITI — principal, interest, taxes, and insurance — as a percentage of gross income, alongside your other debts. This means your homeowners insurance premium isn't a cost you absorb after the loan is approved; it's baked into the calculation that determines your maximum loan amount in the first place.
A higher insurance premium raises your monthly PITI at any given loan amount, which pushes your debt-to-income ratio higher — and if that ratio hits your lender's ceiling before your loan amount reaches the price of the home you want, you qualify for less house, not just a bigger bill. This is exactly why two homes at the same price, in different flood or wind exposure areas, can result in genuinely different loan qualification numbers for the same buyer.
The Coastal Georgia Insurance Market Right Now
This isn't an abstract concern — it's an active, current market condition. Georgia is projected to see a 10% homeowners insurance rate increase in 2026, putting it among the top four states nationally for premium hikes. Severe convective storms — the fast-forming tornado events that come with little warning — are joining hurricane exposure as a driver of rising costs statewide.
Coastal Chatham and Glynn County properties face the most limited carrier options in the state, with separate wind deductibles now standard practice in those areas. In the most storm-vulnerable corridors, a pattern of nonrenewals is already emerging — insurers declining to renew policies rather than absorbing the risk at current rates.
For homeowners who can't secure coverage in the standard market, the Georgia Underwriting Association (GUA) exists as a last-resort option for high-risk coastal and storm-prone properties. GUA coverage is available, but it's generally more limited and more expensive than a standard private policy — worth knowing about, but not something to plan around as your primary strategy.
Why the Same Loan Amount Can Buy Less House Depending on ZIP Code
This is the practical consequence buyers feel directly: your pre-approval amount assumes a specific insurance cost estimate, and if the actual quote for a specific home comes back higher than that estimate, your qualifying loan amount can shrink accordingly — sometimes enough to price a specific home out of reach even though your income and credit haven't changed at all. This is precisely why getting real insurance quotes early in your search, not after you've fallen in love with a specific listing, protects your negotiating position and your accurate sense of what you can actually afford.
How to Lower Your Premium and Get Some Buying Power Back
Ask whether a home meets the FORTIFIED Home™ construction or retrofit standard. This is a nationally recognized wind mitigation certification, and Georgia's own state-run high-risk carrier — the Georgia Underwriting Association — has offered credits for it since 2013, typically 5–10% savings on the wind portion of your premium.
Know your rights under Georgia's newer legal requirement. Under Act 476, passed in the 2023–2024 legislative session, Georgia insurance companies are now required to offer premium discounts to property owners who build or retrofit to FORTIFIED standards — this isn't optional goodwill from a carrier, it's a legal mandate as of March 2025.
Consider a Catastrophe Savings Account if you're planning retrofit work. Georgia enacted legislation in July 2025 allowing homeowners to use tax-advantaged Catastrophe Savings Accounts specifically for retrofit funding and post-disaster repairs — a genuinely useful tool for owners looking to harden a home against wind risk while managing the cost of doing so.
Ask about claims history, roof age, and security system credits on any specific home — these are standard levers that can move a quote meaningfully, and none of them show up automatically unless you ask.
Practical Steps Before You Shop
Get real insurance quotes for your target neighborhoods before you start touring homes seriously — not after you've written an offer. A rough sense of the insurance range in each area you're considering keeps your search grounded in real affordability.
Ask listing agents whether a specific home carries FORTIFIED certification or recent wind mitigation upgrades — this can be a genuine point of leverage in both your insurance quote and your overall offer strategy.
Revisit your pre-approval if your actual insurance quote comes in meaningfully different from your lender's initial estimate — don't assume your original qualifying amount still applies once real numbers are in hand.
Why Work With Kevin Thomas
Understanding how insurance actually affects your buying power — not just your monthly bill — is the kind of detail that changes which homes make sense for your search from the very beginning. Kevin Thomas is a trusted buyer's agent and marketing strategist serving Coastal Georgia, with deep experience helping military families and relocating buyers factor real insurance costs into their affordability from day one.
Working with Kevin means:
✔️ Guidance on getting real insurance quotes early, before you're emotionally invested in a specific home ✔️ Awareness of FORTIFIED Home credits and Georgia's newer legal discount requirements ✔️ Straight talk about where carrier availability is tightest in this market ✔️ Help revisiting your pre-approval if insurance costs shift your real buying power ✔️ An advocate who treats insurance as a genuine affordability factor, not an afterthought
Your Next Step
Call or text Kevin Thomas: (912) 980-6153 Before you assume your pre-approval number is your real buying power, make sure insurance costs have been factored in accurately.
Kevin Thomas with Level 10 Real Estate Group helps Coastal Georgia buyers understand what they can actually afford — insurance included, not added as a surprise later.
Karyn Thomas
Lead Listing Agent/ Co-Team Owner | Level 10 Real Estate Group | Keller Williams Coastal Area Partners
or another way